

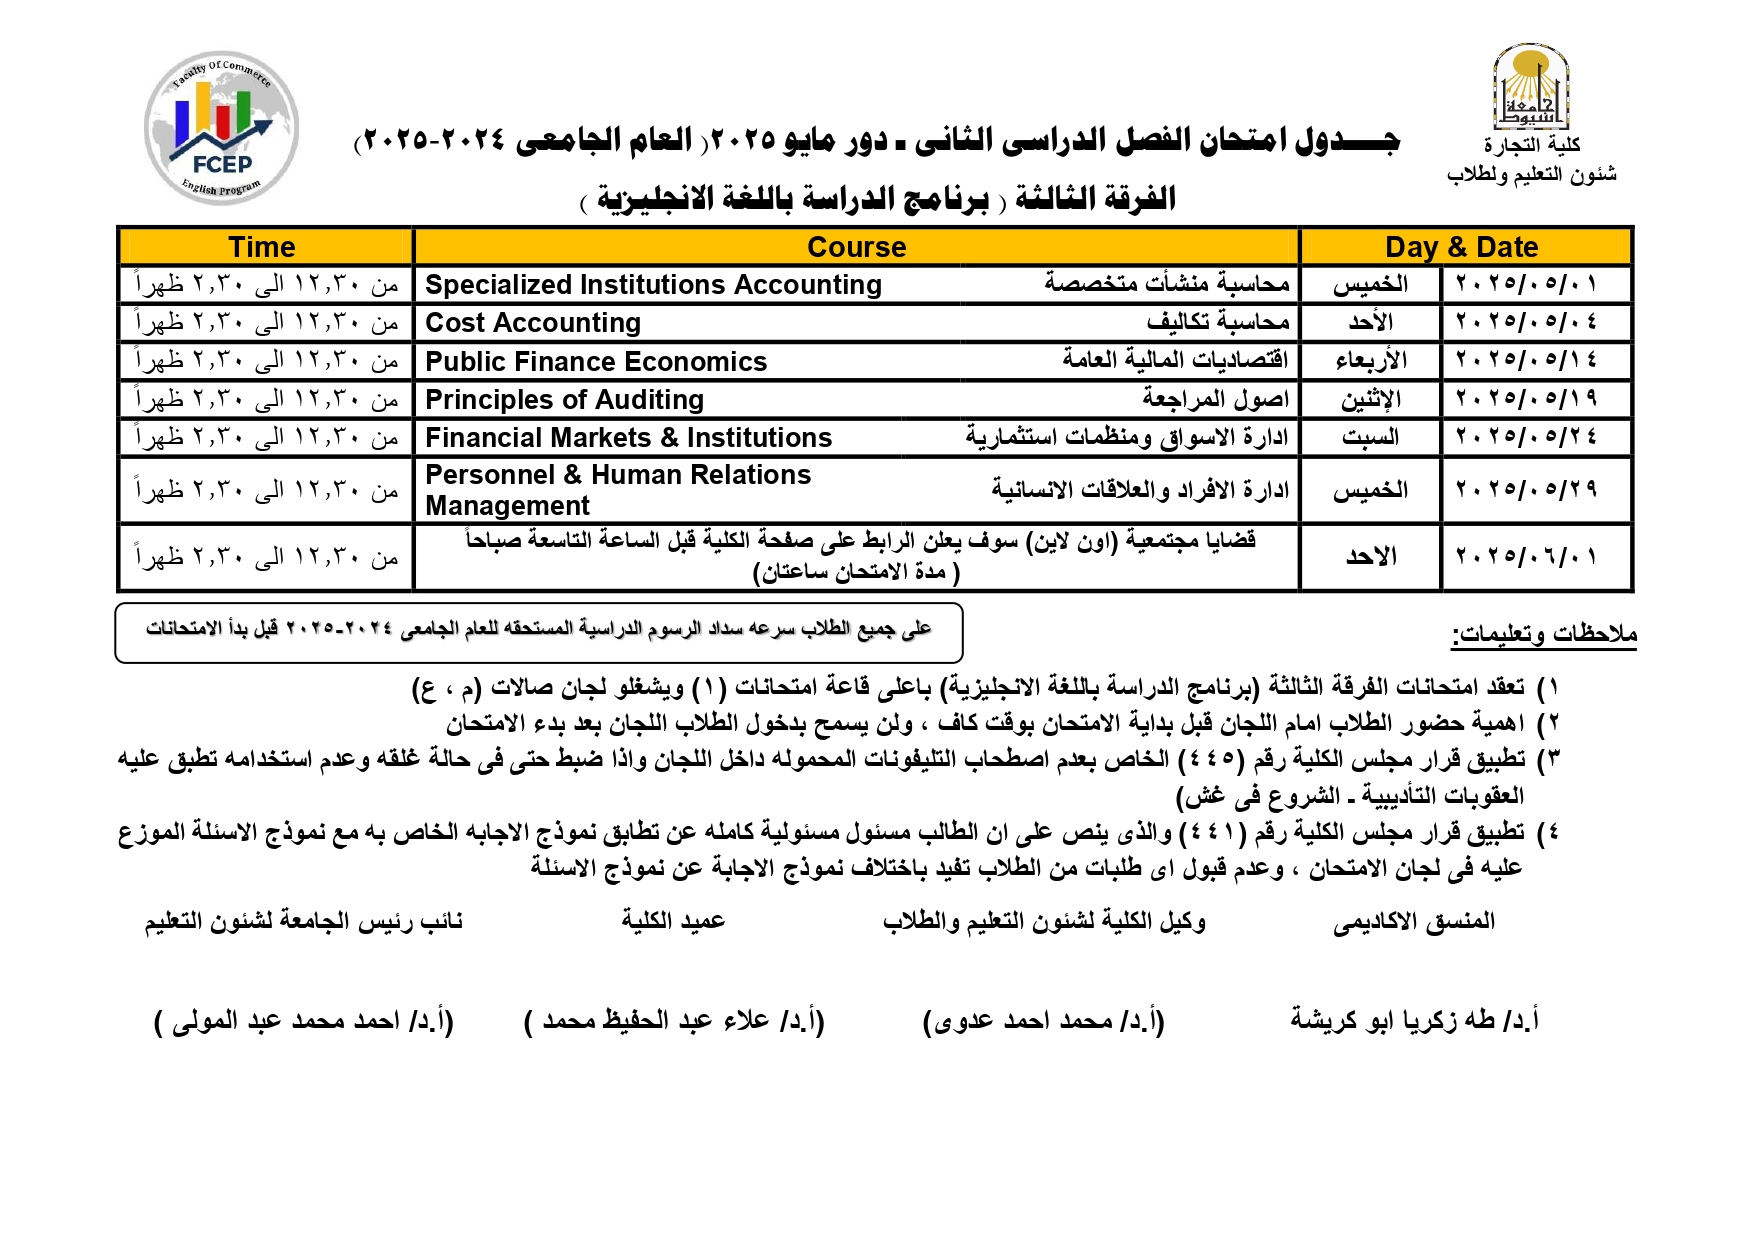
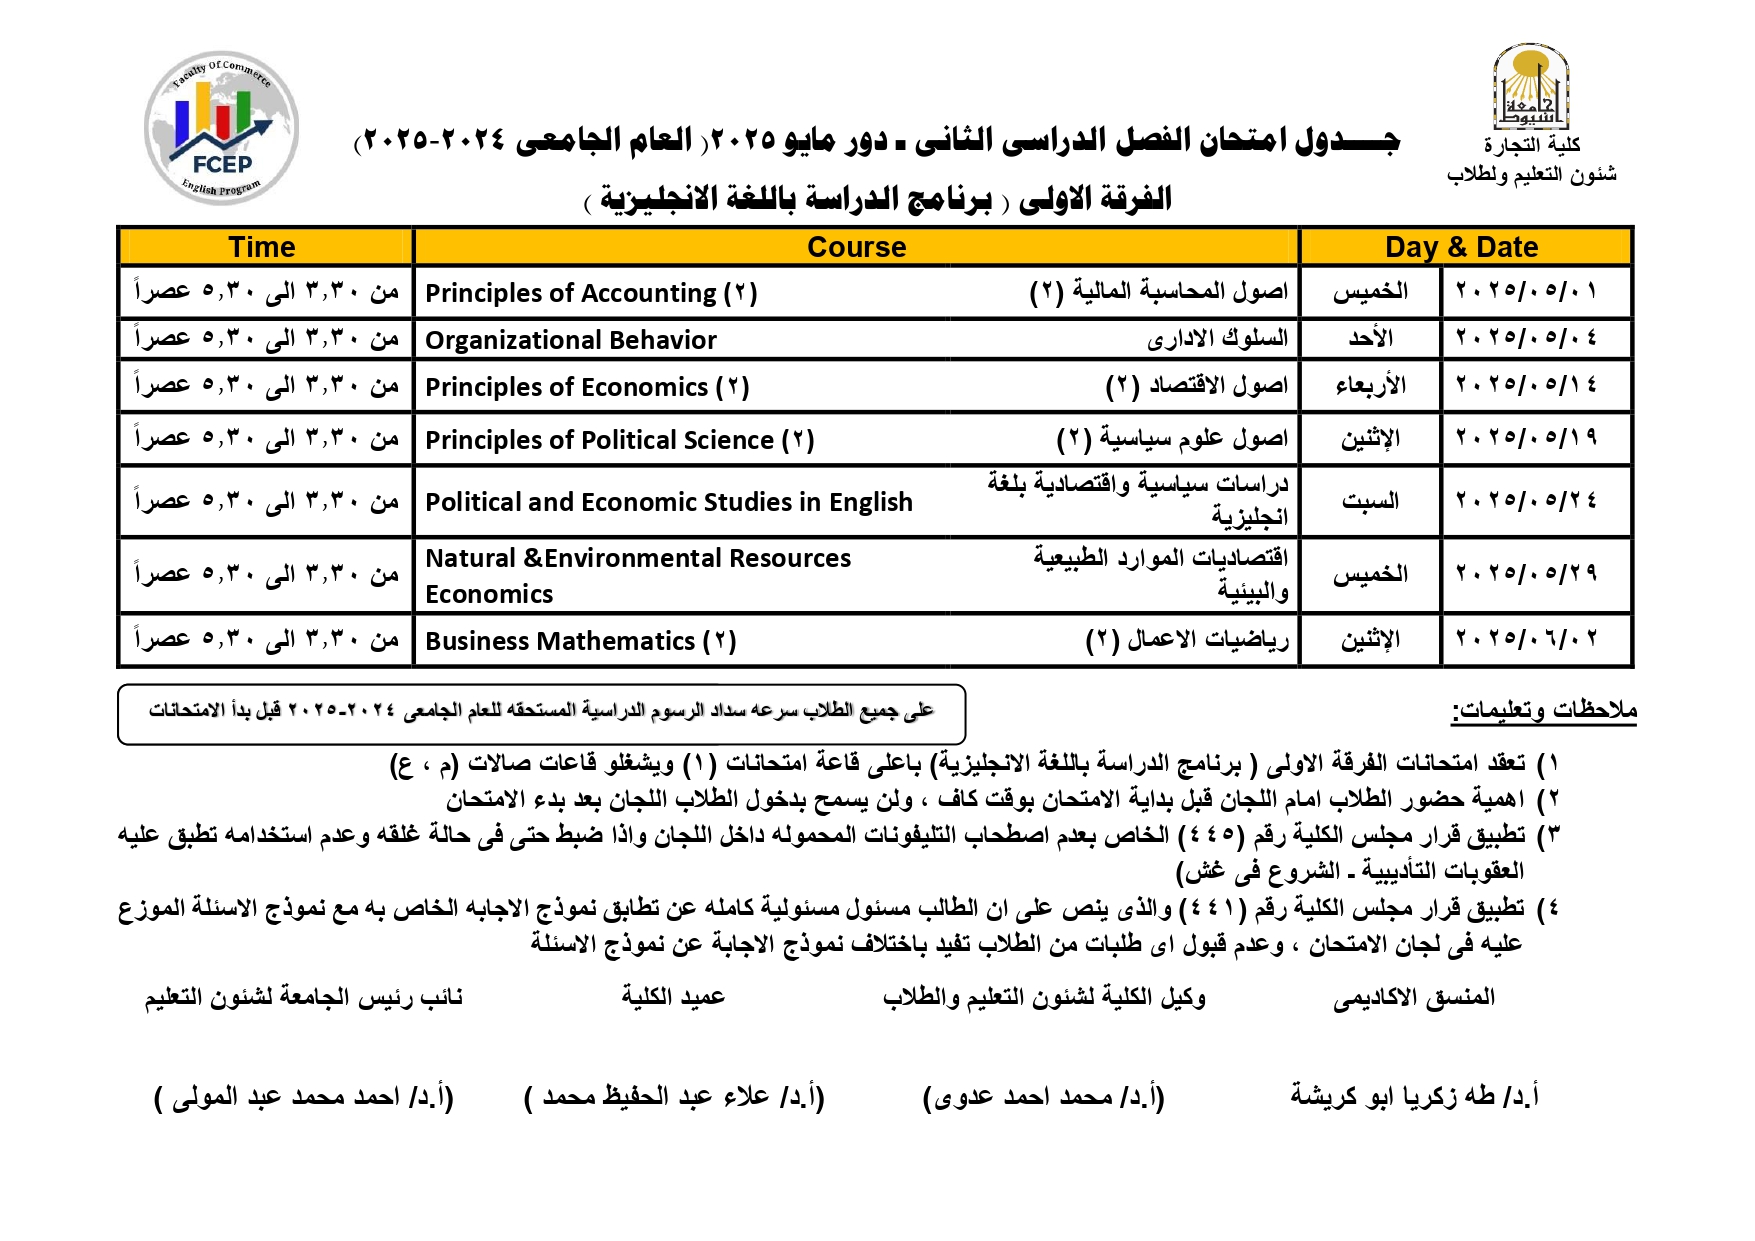
Exam schedule for second semester - May 2025, fourth year (study program in English)
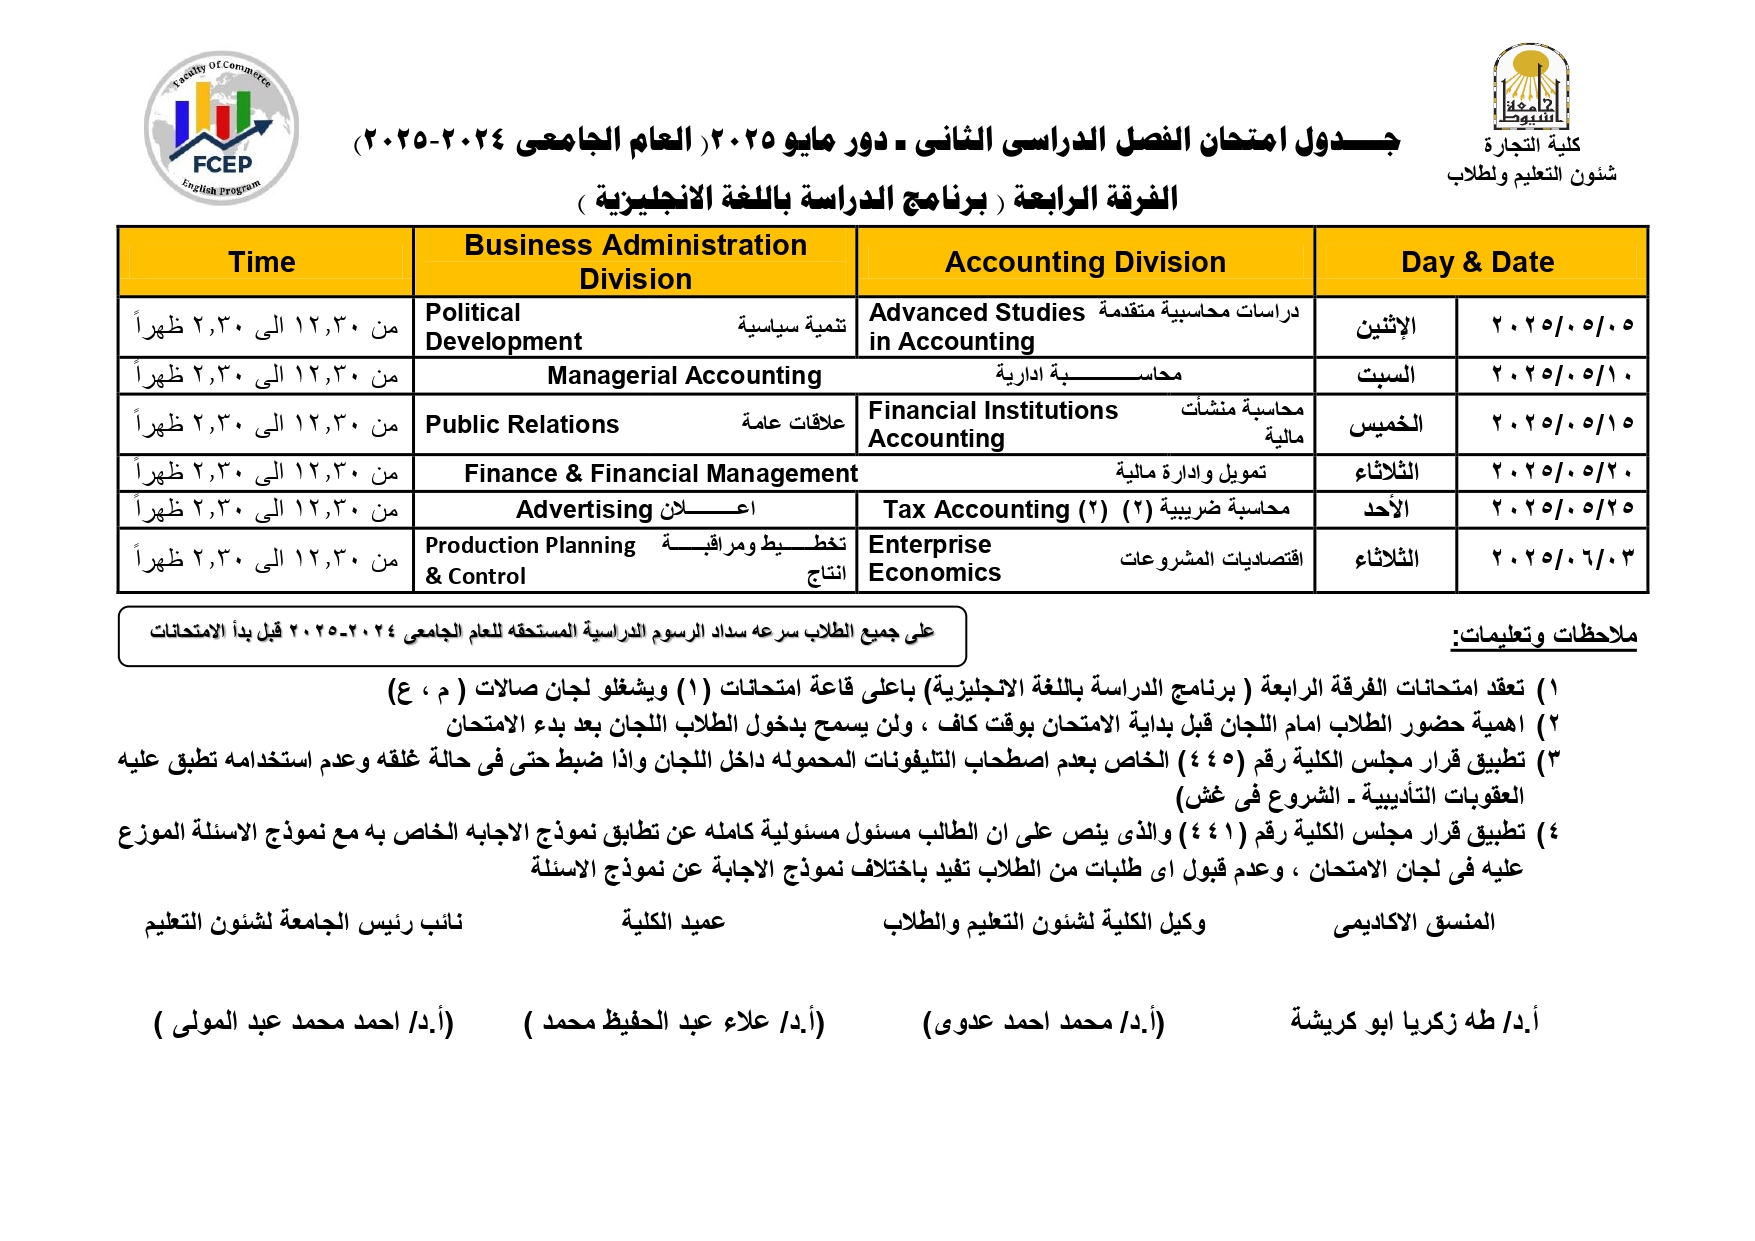
Exam schedule for second semester - May 2025, first year (regularity - directed affiliation)
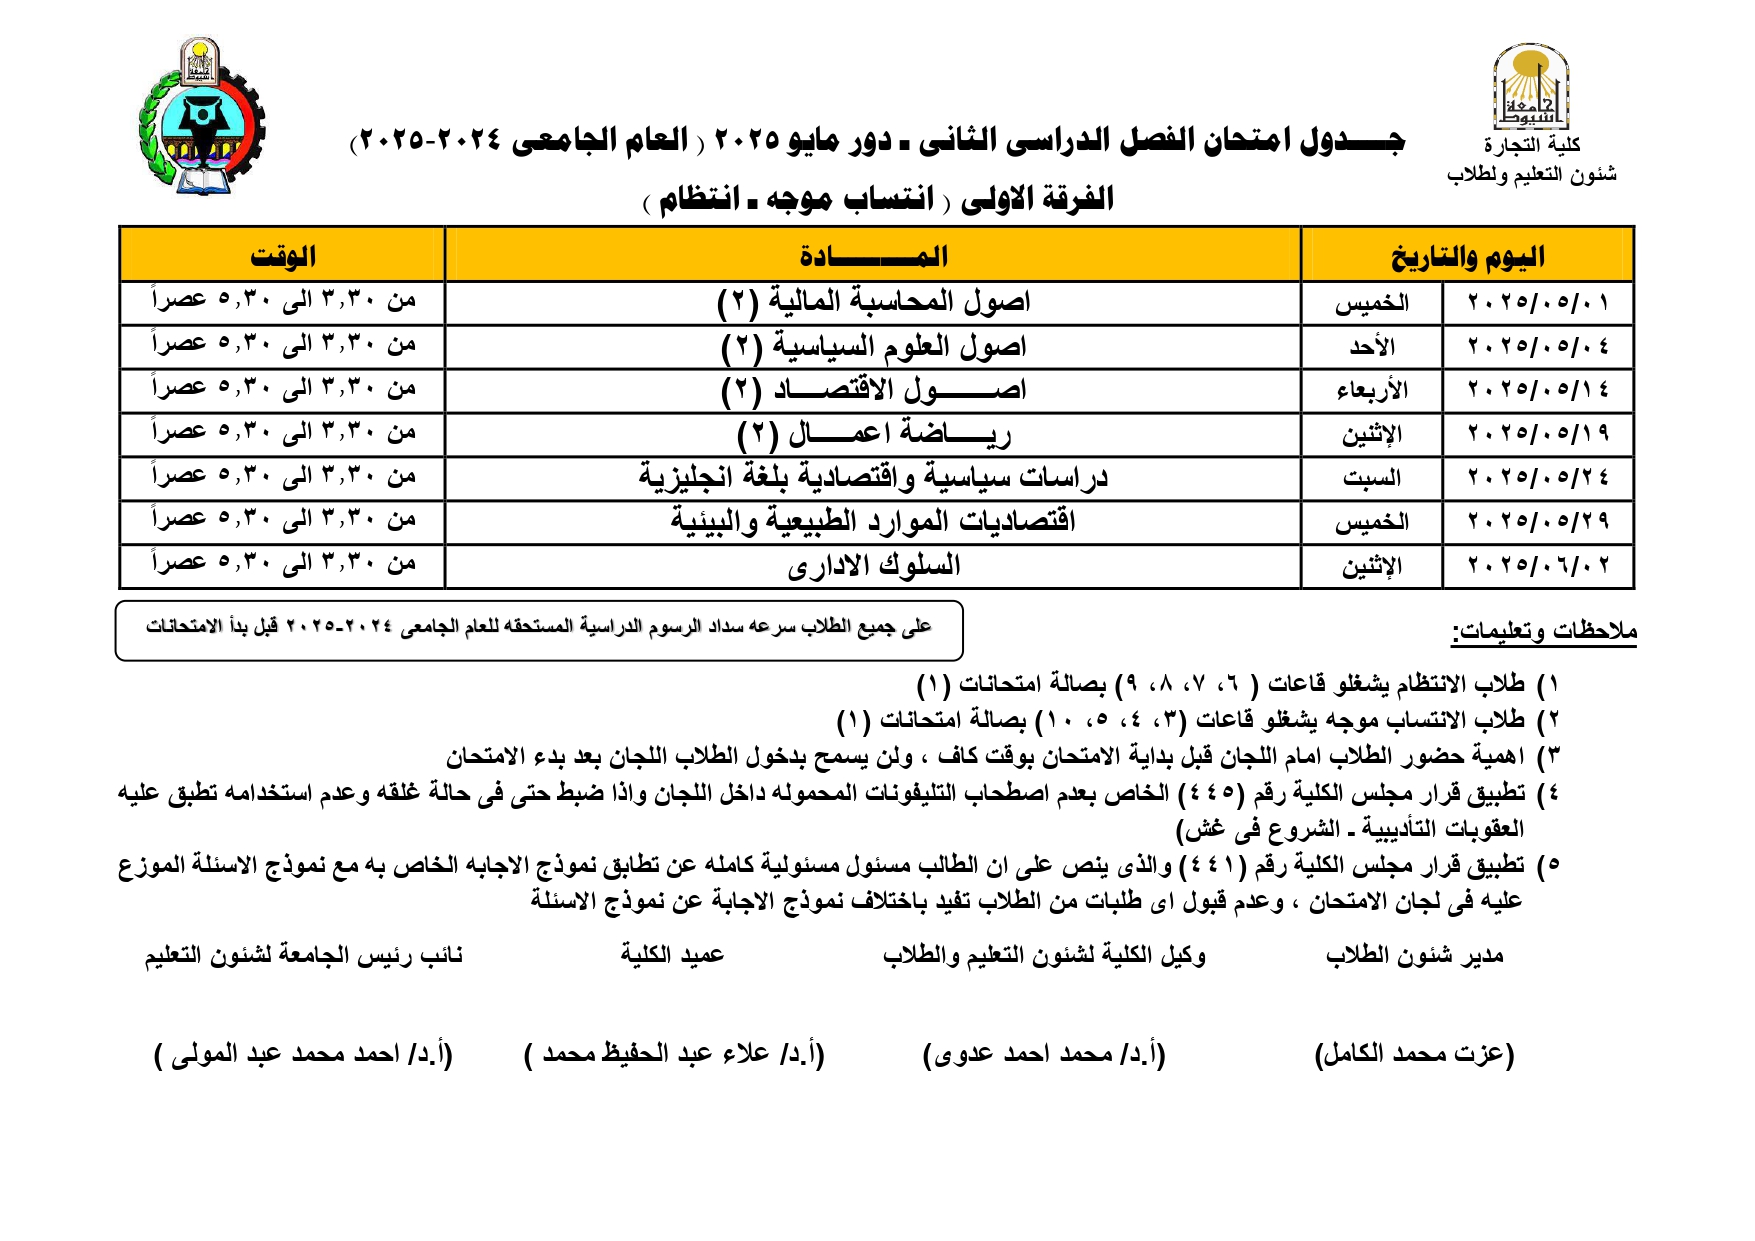
Exam schedule for second semester - May 2025, second year (regularity - directed affiliation)
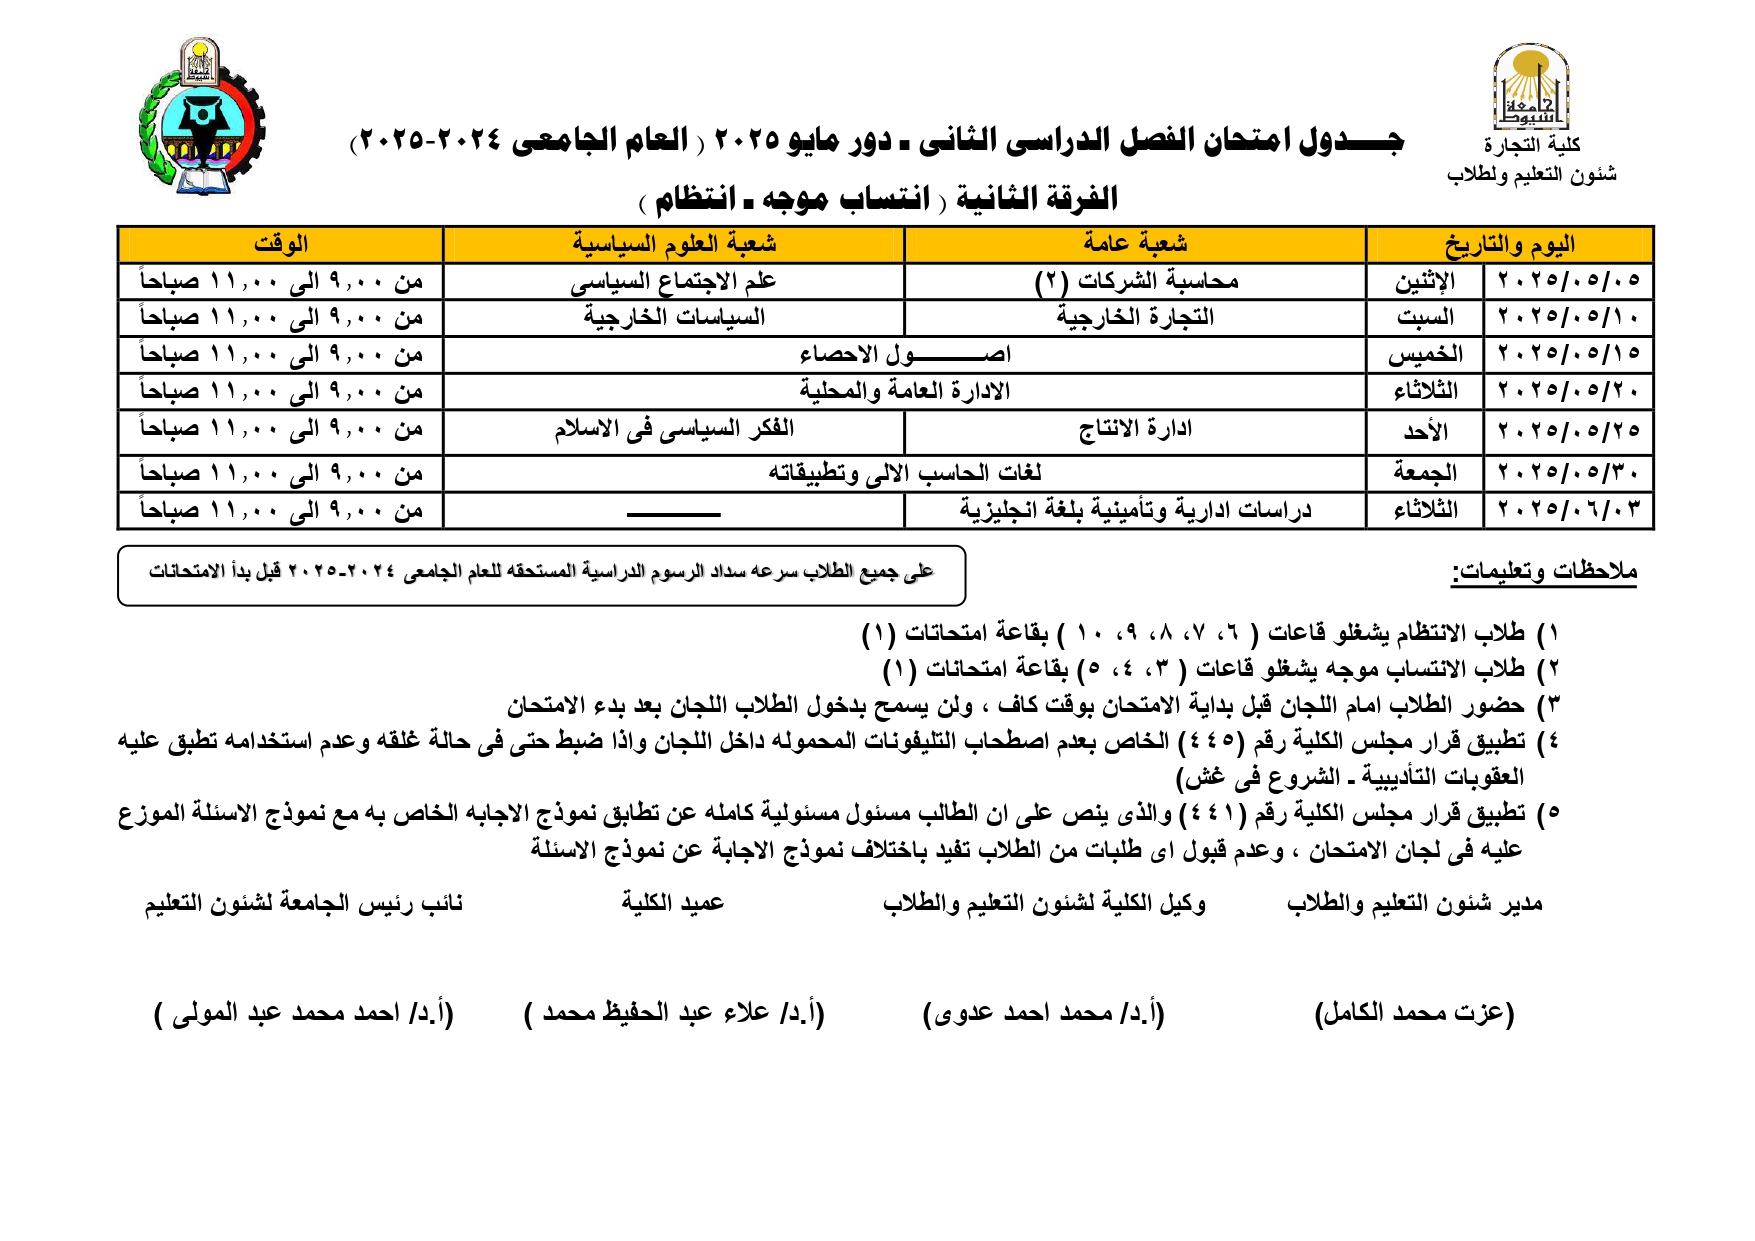
Exam schedule for second semester - May 2025, third year (regularity - directed affiliation)
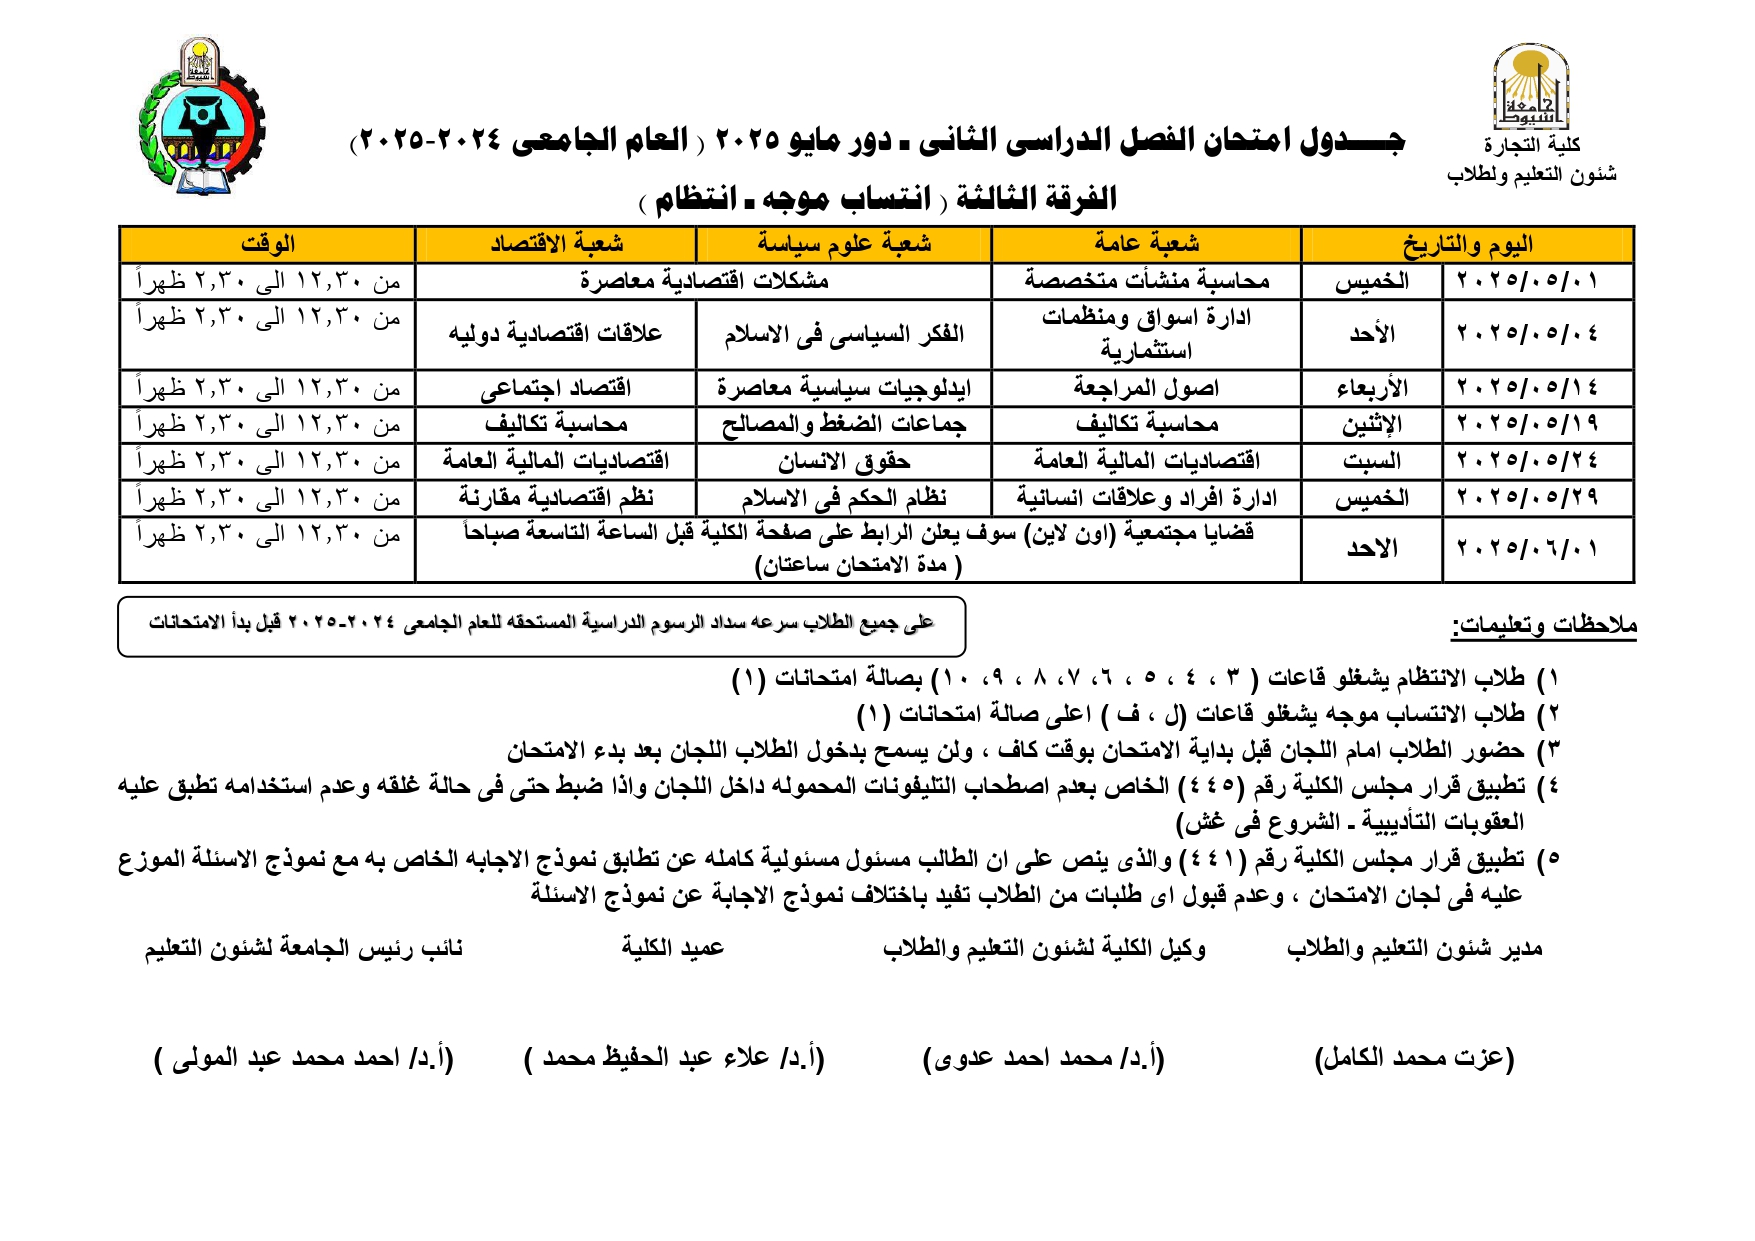
Exam schedule for second semester - May 2025, fourth year (regularity - directed affiliation)
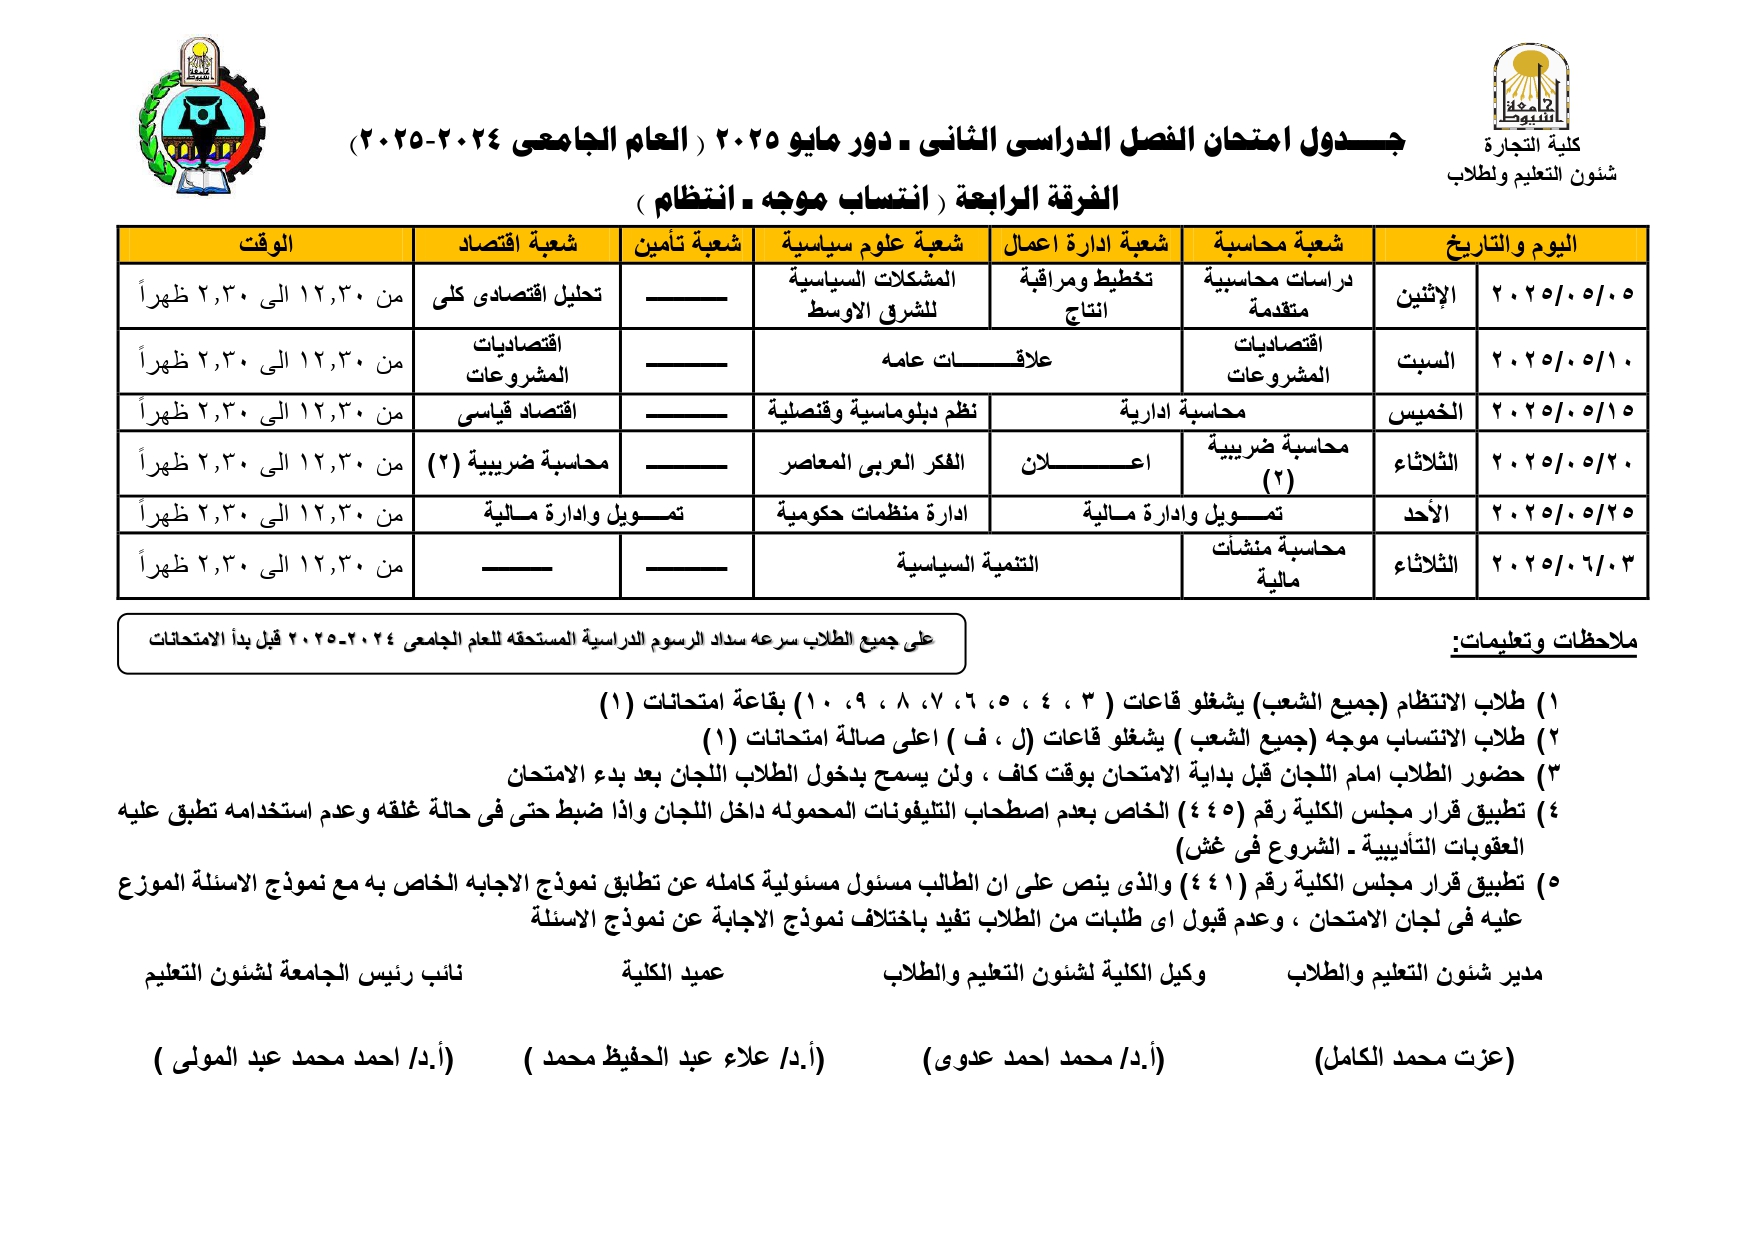
Exam schedule for second semester - May 2025, first year (study program in English)
The impact of integrated reporting quality on the cost of equity capital: evidence from Asia
Research Abstract
Purpose– This paper aims to examine the impact of the quality of integrated reporting (IR) on the cost of equity capital in the voluntary Asian context. Design/methodology/approach– This study uses OLS regression to analyze the impact of IR quality on the cost of equity, using a sampleof Asian firmsthat issued IR andarepresented on theInternational Integrated Reporting Council website from 2015 to 2022. IR quality is evaluated through content analysis. To ensure the robustness of the findings, this study incorporates alternative cost of capital measures, propensity score matchingandinstrumental variable estimation. Findings– IR quality negatively influences the cost of capital. Additional analysis shows that this negative impact is more pronounced in profitable firms and firms with a higher need for external financing. In addition, further analysis shows that the negative impact remains significant during the COVID-19 pandemic period. In addition, the findings reveal that earnings quality and analyst forecast accuracy serve as mediators in the relationship between IR quality and the cost of capital. Practical implications– Understanding how IR quality influences the cost of capital is vital for investors, policymakers, regulators and companies. Originality/value– This study is unique in concentrating on the effect of the quality of IR on the cost of capital in the voluntary Asian context. This region has received little attention in previous research. This study also adds to the literature by showing the mediating role of earnings quality and analyst forecast accuracy on the relationship between IR quality and cost of capital. Keywords Integrated reporting, Cost of capital, Earnings quality, Asia Paper type Research paper
Research Date
Research Department
Research File
10-1108_jfra-06-2024-0318.pdf
(240.94 KB)
Research Journal
Journal of Financial Reporting and Accounting
Research Member
Research Pages
1-23
Research Publisher
EmeraldPublishing Limited
Research Vol
Vol. ahead-of-print
Research Website
https://www.emerald.com/insight/1985-2517.htm
Research Year
2025
Does ERP Adoption Affect Stock Price Volatility? Evidence from Egypt
Research Abstract
This study explores the association between ERP adoption and stock price volatility (SPV). An ERP software reshapes information collected, processed, and disseminated. We examine whether ERP usage influences the stock price volatility of Egyptian firms. Our investigation is among the first to examine how ERP usage affects SPV, an overall outcome measure of a firm’s information environment. The Findings document that ERP has a significant and negative association with SPV. Stock price volatility (SPV) relationships have expanded the literature on ERP facts. ERP is essential for both strategic and operational logistics decisions. This study also gives strong evidence that ERP-adopted firms help to reduce the risk of stock price volatility and build a good relationship with the shareholders. Overall, it showed the financial effect of ERP in the emerging economy context of Egypt. OLS Regression Analysis 115 organizations in Egypt were edited in 1150 observations registered from 2011 to 2020 on the Egyptian Stock Exchange (ESE). The main results of tests are robust after analysis with a cluster of the standard errors by companies' change of critical variables.
Research Date
Research Department
Research File
Research Journal
International Journal of Economics, Business and Management Research
Research Member
Research Pages
104-124
Research Publisher
International Journal of Economics, Business and Management Research
Research Vol
Vol. 7, No.11; 2023
Research Year
2023
The impact of integrated reporting quality on the cost of equity capital: evidence from Asia
Research Abstract
Purpose – This paper aims to examine the impact of the quality of integrated reporting (IR) on the cost of equity capital in the voluntary Asian context.
Design/methodology/approach – This study uses OLS regression to analyze the impact of IR quality on the cost of equity, using a sample of Asian firms that issued IR and are presented on the International Integrated Reporting Council website from 2015 to 2022. IR quality is evaluated through content analysis. To ensure the robustness of the findings, this study incorporates alternative cost of capital measures, propensity score matching and instrumental variable estimation.
Findings – IR quality negatively influences the cost of capital. Additional analysis shows that this negative impact is more pronounced in profitable firms and firms with a higher need for external financing. In addition, further analysis shows that the negative impact remains significant during the COVID-19 pandemic period. In addition, the findings reveal that earnings quality and analyst forecast accuracy serve as mediators in the relationship between IR quality and the cost of capital.
Practical implications – Understanding how IR quality influences the cost of capital is vital for investors, policymakers, regulators and companies.
Originality/value – This study is unique in concentrating on the effect of the quality of IR on the cost of capital in the voluntary Asian context. This region has received little attention in previous research. This study also adds to the literature by showing the mediating role of earnings quality and analyst forecast accuracy on the relationship between IR quality and cost of capital.
Keywords Integrated reporting, Cost of capital, Earnings quality, Asia
Research Date
Research Department
Research Journal
Journal of Financial Reporting and Accounting
Research Member
Research Publisher
Emerald Publishing Limited
Research Rank
Scupos- WoS (Q1)
Research Vol
ahead-of-print.
Research Website
https://doi.org/10.1108/JFRA-06-2024-0318
Research Year
2025